Ontario's Cottage Market Cools: What London Families Should Consider Before Buying Waterfront
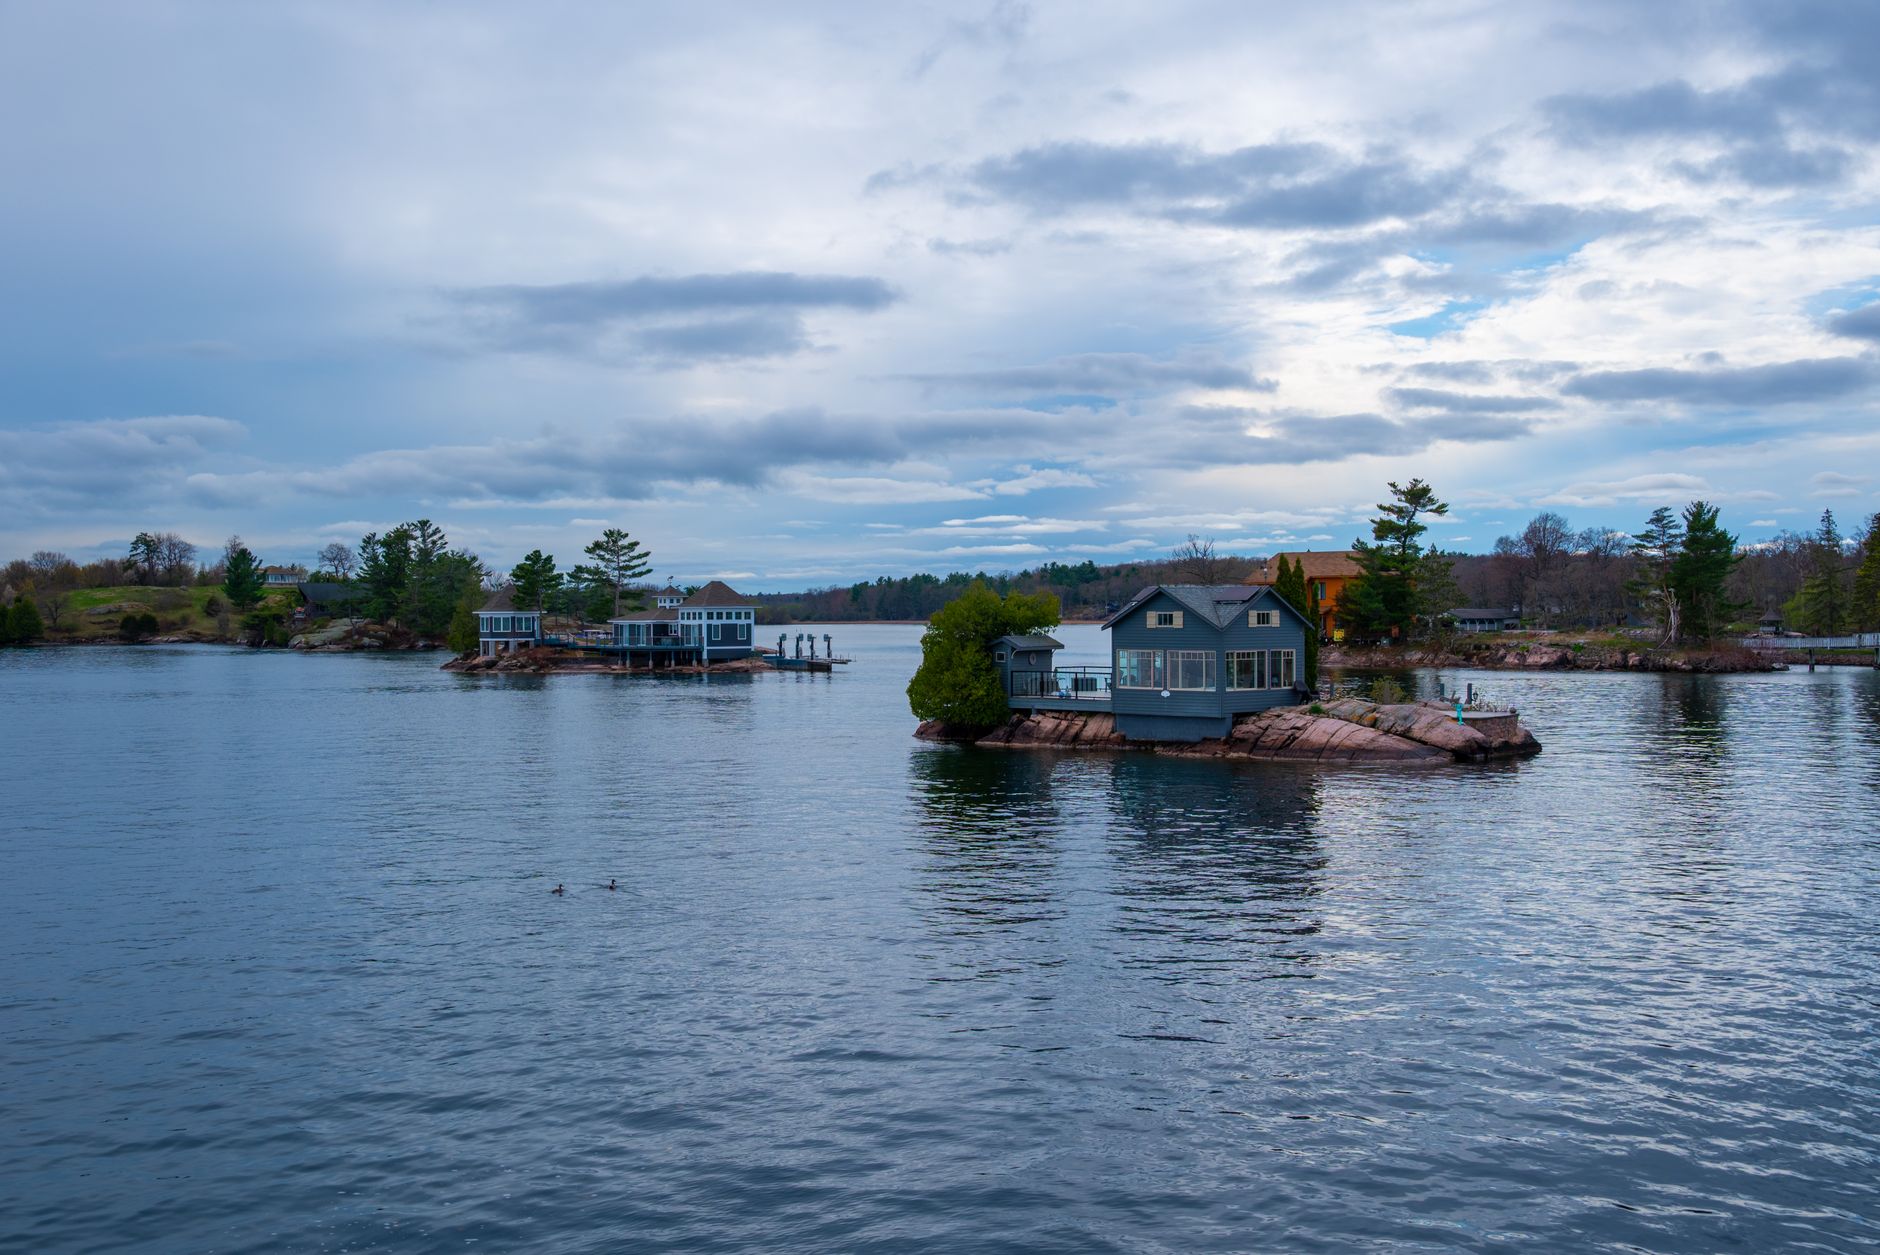
The Pandemic Cottage Rush Is Over — Now What?
For many London families, the dream of owning a cottage has long been part of the plan. After years of summer weekends spent driving to Grand Bend, Port Stanley, or the lakes north of the city, the idea of having your own waterfront retreat is understandably appealing.
But Ontario's cottage market has shifted dramatically since the pandemic boom, and understanding these changes could save London buyers hundreds of thousands of dollars — or help them avoid a costly mistake.
The Current Reality
The latest data tells a sobering story:
- Nationally, waterfront home prices slipped 5.2% to a median of $717,600 in 2025 - Listings are sitting on the market significantly longer than during the pandemic - In Haliburton — a popular destination for London cottage seekers — prices are down roughly 20% from peak levels - Inventory has surged, with some months seeing more than double the listings compared to pandemic lows
Forecasts for 2026 are mixed, with some analysts predicting a modest 2% price increase while others expect prices to fall another 8% with sales volume dropping 10% to 15%.
A Tale of Two Markets
What's fascinating is how the cottage market has split into distinct segments:
Trophy Waterfront ($4M+): High-end properties with premium lake frontage are holding value remarkably well. Buyers in this segment are often paying cash, making them less sensitive to interest rate pressures.
Mid-Range and Entry-Level Cottages: This is where the correction is most visible. Properties that sold for $600,000 to $900,000 during the pandemic frenzy are now struggling to find buyers at those levels.
What This Means for London Buyers
If you're a London family considering cottage ownership, this market shift creates both opportunities and considerations:
Negotiating Power Has Returned: Unlike 2021 when cottages sold in bidding wars sight-unseen, today's buyers have leverage. Properties are sitting longer, and sellers are increasingly motivated.
Due Diligence Matters More: With less competition, you have time to conduct proper inspections, review septic and well reports, and understand shoreline regulations. Don't skip these steps.
Financing Is Trickier: Cottage mortgages often come with different requirements than primary residences. Expect higher down payment requirements (often 20% to 35%) and potentially higher rates for seasonal properties.
Comparing Costs: Cottage Ownership vs. London Real Estate
Before committing to cottage ownership, consider the full picture. A $500,000 cottage purchase involves:
- Mortgage payments (likely at higher cottage-specific rates) - Property taxes (which vary dramatically by township) - Insurance (waterfront properties carry premium rates) - Maintenance and winterization - Travel costs for weekend trips
For some London families, that same investment might better serve them as a renovation to their Byron bungalow, a move to a larger home in Lambeth with more backyard space, or even as a down payment on a rental property that generates income.
The Alternative: Maximizing London Living
London offers remarkable outdoor lifestyle options that sometimes get overlooked in the cottage dream:
- The Thames Valley Parkway provides over 40 kilometres of trails - Springbank Park offers riverside recreation minutes from neighbourhoods like Byron and Westmount - Fanshawe Conservation Area provides lake access without the ownership burden - Boler Mountain offers four-season recreation right in the city
This isn't to say cottage ownership is wrong — for many families, it's a cherished tradition and worthwhile investment. But the decision should be made with clear eyes about current market conditions and total costs.
If You're Still Interested
For London buyers serious about cottage hunting, consider these strategies:
1. Be patient: Inventory is rising and prices may soften further 2. Look beyond peak areas: Regions that didn't see extreme pandemic appreciation may offer better value 3. Consider co-ownership: Splitting costs with family or friends can make ownership more accessible 4. Rent first: Spend a season renting in your target area before committing
---
Whether you're weighing cottage ownership against upgrading your London home, or you're ready to make a move in either market, let's talk strategy. Contact Nickey Calford at Calford & Co. Real Estate Team to discuss how your real estate goals fit into the bigger picture of your family's lifestyle and finances.
Ready to Make Your Move?
Get personalised advice from London's trusted real estate experts. Contact Calford & Co. today to discuss your property goals.